Most operators facing a kitchen-down window assume the decision is financial. It is really a duration question wearing a financial costume. Across the US economy, 82% of businesses acquiring equipment use some form of financing rather than paying cash outright, according to the Equipment Leasing & Finance Foundation's Horizon Report, which puts total equipment and software investment at $2.3 trillion. Almost nobody writes the cheque. The useful question is not whether to tie up capital but how long you will actually need a kitchen, because that single number decides whether buying, renting or financing a mobile kitchen is the cheaper mistake to make. This breakdown walks the three paths, what each really costs, and which reader each one suits.
Start With Duration, Not Price
Duration is the variable that reorders everything else. A kitchen you need for five months and a kitchen you need for five years are not the same purchase with different numbers attached; they sit in different budget lines, get approved by different people, and are governed by different tax rules. Fix the timeline first.
Two timelines matter, and operators confuse them. There is the length of the disruption — the renovation window, the repair period, the season. Then there is how long your organisation needs mobile capacity at all, across every site. A club with one clubhouse renovation has a five-month problem. A group cycling through eight properties over a decade has a different one.
Tip: Write both numbers down before you ask anyone for a price. Every question in this article resolves once you have them.

Buying: What the Capital Actually Buys You
Buying converts an operating expense into an asset on your balance sheet. You own the unit outright, configure it however you like, and carry it for as long as it lasts. You also carry everything that comes with ownership: maintenance, compliance renewals, storage between deployments, insurance, and the eventual problem of disposal.
The tax treatment is the part most operators underweight, and it is genuinely favourable. Under the IRS instructions for Form 4562, the Section 179 maximum deduction for tax years beginning in 2025 is $2,500,000, reduced dollar-for-dollar once section 179 property placed in service exceeds $4,000,000. A 100% special depreciation allowance applies to most qualified property acquired after 19 January 2025. For an organisation with taxable income to shelter, that changes the first-year arithmetic considerably.
What it does not change is utilisation. An owned unit that sits idle between projects still costs money every month. Ownership rewards operators who will keep the asset working — disaster-response organisations, catering companies with dedicated equipment, hospitality groups running continuous multi-site programmes. It punishes everyone else.
Note: Mobile Culinaire rents. We do not sell units, so nothing here is a pitch — if your timeline genuinely points to ownership, the purchase market is a separate set of vendors.

Renting: What the Monthly Figure Covers
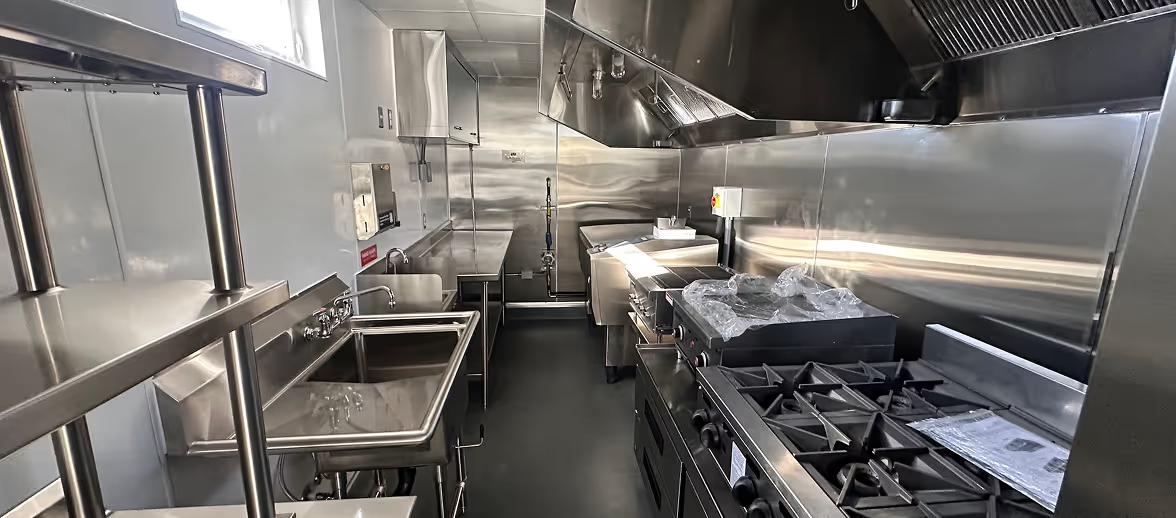
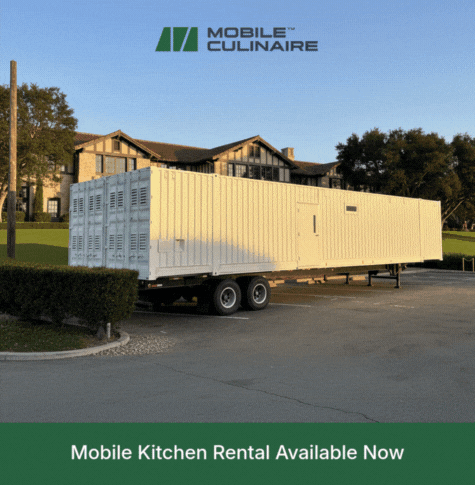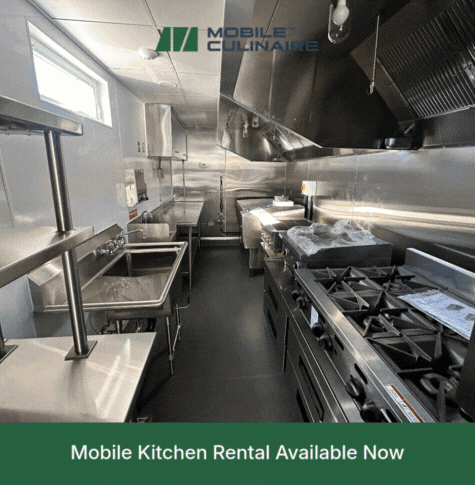
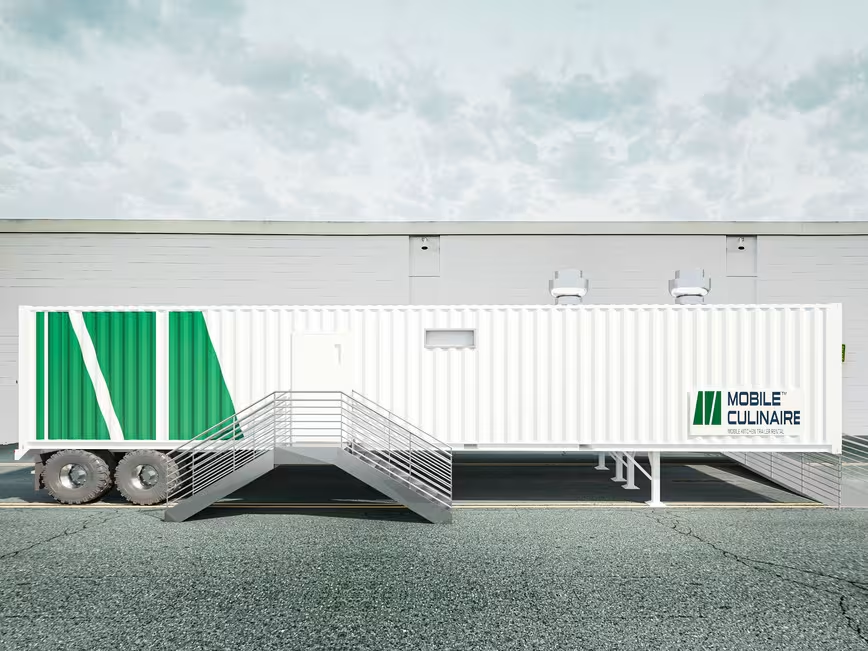
Renting removes the asset question altogether. You pay a monthly rate, the unit arrives configured and code-compliant, and it leaves when the project ends. A Mobile Culinaire unit rents for $8,000 to $25,000 a month, set by which of the four configurations you take and what goes inside it.
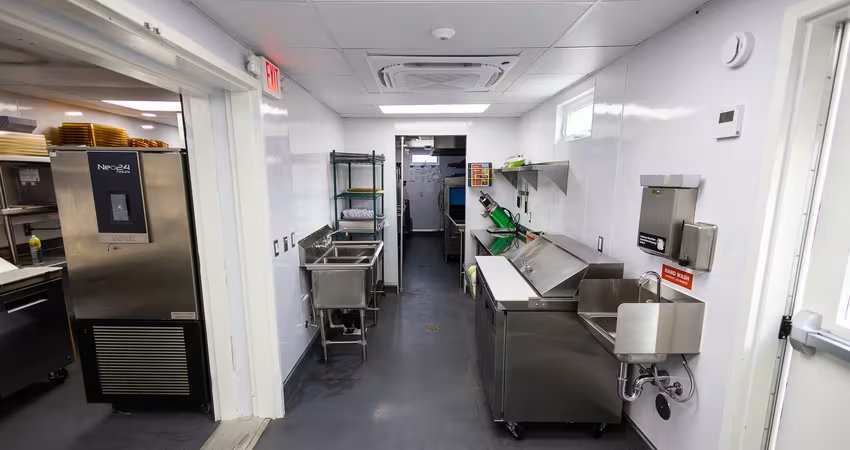
One month is the shortest term available, and the monthly figure covers more than steel. It includes delivery, installation assistance, project management and removal assistance, plus the technical documentation and installation guides. That matters most in the scenario this reader dreads: the kitchen goes down without warning, you are already coordinating insurance, contractors and a damage assessment, and a fragmented vendor search is the last thing you can absorb.
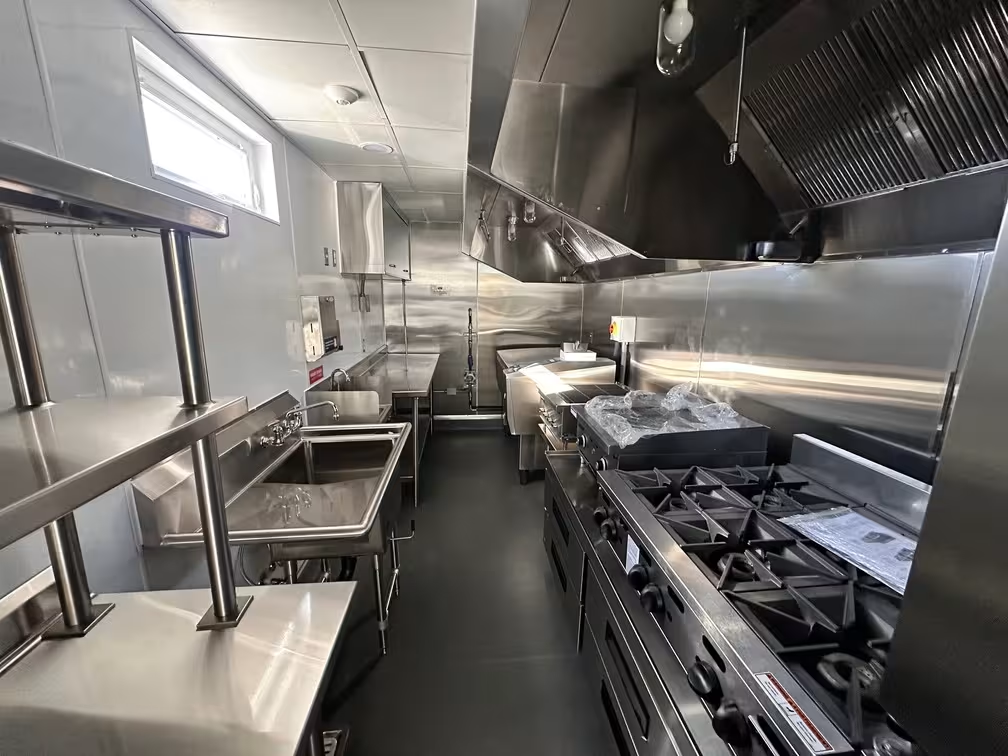
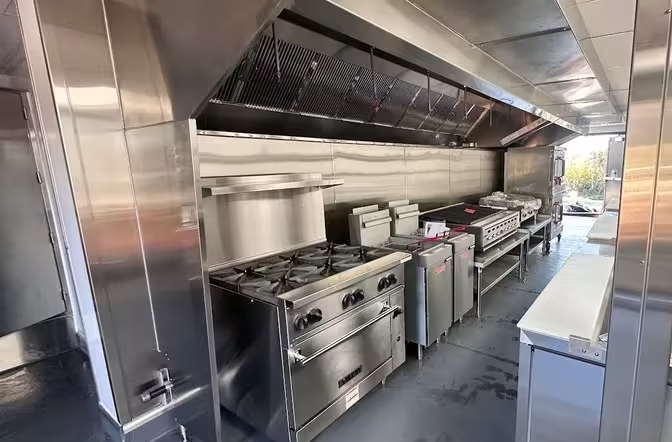
It is also where the quality gap shows. A retrofitted trailer rents cheaply for a reason: undersized power, thin insulation, and equipment that gives out once it runs every service for months rather than a couple of days. A purpose-built unit is specified to the standard a permanent kitchen is held to. Our rental cost breakdown itemises what moves the monthly figure, and the retrofitted-trailer comparison covers the gap in detail.
Financing a Purchase: The Third Path
Financing sits between the two: you acquire the asset, but a lender fronts the capital and you repay it over a term. This is the path the Horizon Report's 82% figure describes, and the Equipment Leasing and Finance Association exists because it is how most American businesses buy equipment.
Two SBA routes apply. A 7(a) loan goes up to $5 million and explicitly covers "purchasing and installation of machinery and equipment." A 504 loan goes up to $5.5 million but carries a disqualifier worth knowing early: it funds "long-term machinery and equipment with a useful remaining life of a minimum of 10 years." A unit acquired to cover a six-month renovation does not qualify.
There is an accounting consequence too. Under FASB Topic 842, lessees recognise a right-of-use asset and a lease liability — meaning a financed lease generally lands on the balance sheet in a way a short operating rental does not. If your board reads the balance sheet closely, involve your controller before you commit. Our guide to rental terms and extensions covers how long a rental can actually run.
Buy, Rent or Lease a Mobile Kitchen: The Paths Side by Side
Once the timeline is fixed, the three paths separate cleanly on five questions: how much capital leaves the business, where the unit sits in your accounts, who maintains it, who absorbs the idle months, and what pattern of use each one rewards. Read the table by your own duration rather than down the columns.
| What you're weighing | Buy outright | Rent | Finance a purchase |
|---|---|---|---|
| Capital required | Full cost upfront | None | Deposit plus repayments |
| Balance sheet | Asset you own | Largely off it | Asset and liability |
| Who maintains it | You | The provider | You |
| Idle-period cost | Yours to carry | None — it leaves | Yours to carry |
| Best when | Continuous multi-site use | A defined project window | Long-term need, limited cash |

Which One Fits Your Situation
Match the instrument to the timeline, then sanity-check it against who carries the risk. A defined disruption — a renovation, a repair, a season — is a rental. Continuous use across a portfolio is an ownership question. A long-term need with capital committed elsewhere is a financing question.
The objection worth pre-empting is the one boards raise: renting looks more expensive than toughing it out or taking the cheap retrofit. Against a monthly rate, maybe. Against an extended closure with no interim revenue, and against a stopgap that fails mid-service and compounds the original problem, the arithmetic is different — though we deliberately do not publish a savings percentage, because we do not have one worth standing behind. Run the numbers on your own dues and covers.
What we will say plainly: Mobile Culinaire rents purpose-built mobile kitchens, short term to long term, from one month upward. That is the whole offer. If a window is already on your calendar, start the conversation while the dates are still movable, and see how renting compares with owning a commercial kitchen if the facility question is still open.
Disclaimer
Tax treatment, depreciation elections and lease accounting depend on your entity type, taxable income and reporting obligations, and the figures cited here apply to specific tax years. Loan eligibility varies by lender and applicant. Confirm any tax, accounting or financing position with your own CPA, controller or lender before relying on it. We are not tax or financial advisers.

Conclusion
Buying, renting and financing a mobile kitchen answer three different questions, and yours is how long you need the kitchen. Fix that number, decide who carries the maintenance and the idle months, then check the tax and balance-sheet consequences with someone qualified. See the mobile kitchen configurations and work back from the service you have to protect.
People Also Ask
What is the difference between renting and leasing a mobile kitchen?
In practice the words overlap, and the distinction that matters is accounting rather than vocabulary. A short rental is an operating cost that ends when the unit leaves. A finance lease is an acquisition instrument: under FASB Topic 842 a lessee recognises a right-of-use asset and a lease liability, so it shows up on the balance sheet. Ask which one a quote describes.
When does buying a mobile kitchen make more sense than renting?
When utilisation stays high. Ownership suits organisations that will keep a unit working continuously — multi-site hospitality groups, catering operations with dedicated equipment, disaster-response bodies. A single defined disruption rarely justifies it, because an owned unit sitting idle between projects still costs money every month while earning nothing.
How much does it cost to rent a mobile kitchen?
Expect $8,000 to $25,000 a month, the range driven by unit size and the equipment schedule, with one month the shortest term on offer. Delivery, installation assistance, project management and removal assistance sit inside that figure. Outside it: your utilities and their running costs, the site connections themselves, any decks or ramps, and the permit.

Testimonial
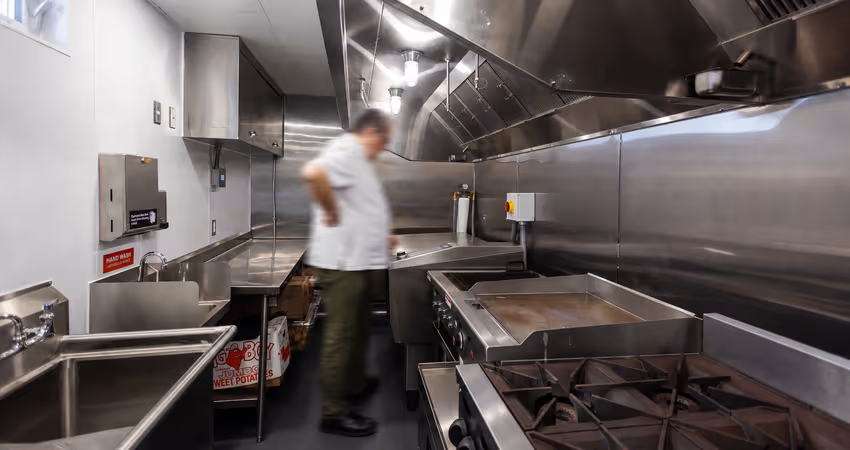
"What is standing out when you look at the mobile kitchen operation is the efficiency that we can really achieve because it's built for that."
Tell us about your kitchen needs and request a quote.

Turnkey mobile kitchen
Proudly made in-house in the USA
Commercial grade kitchen equipment
Code-compliant
Trusted by Industry Leaders